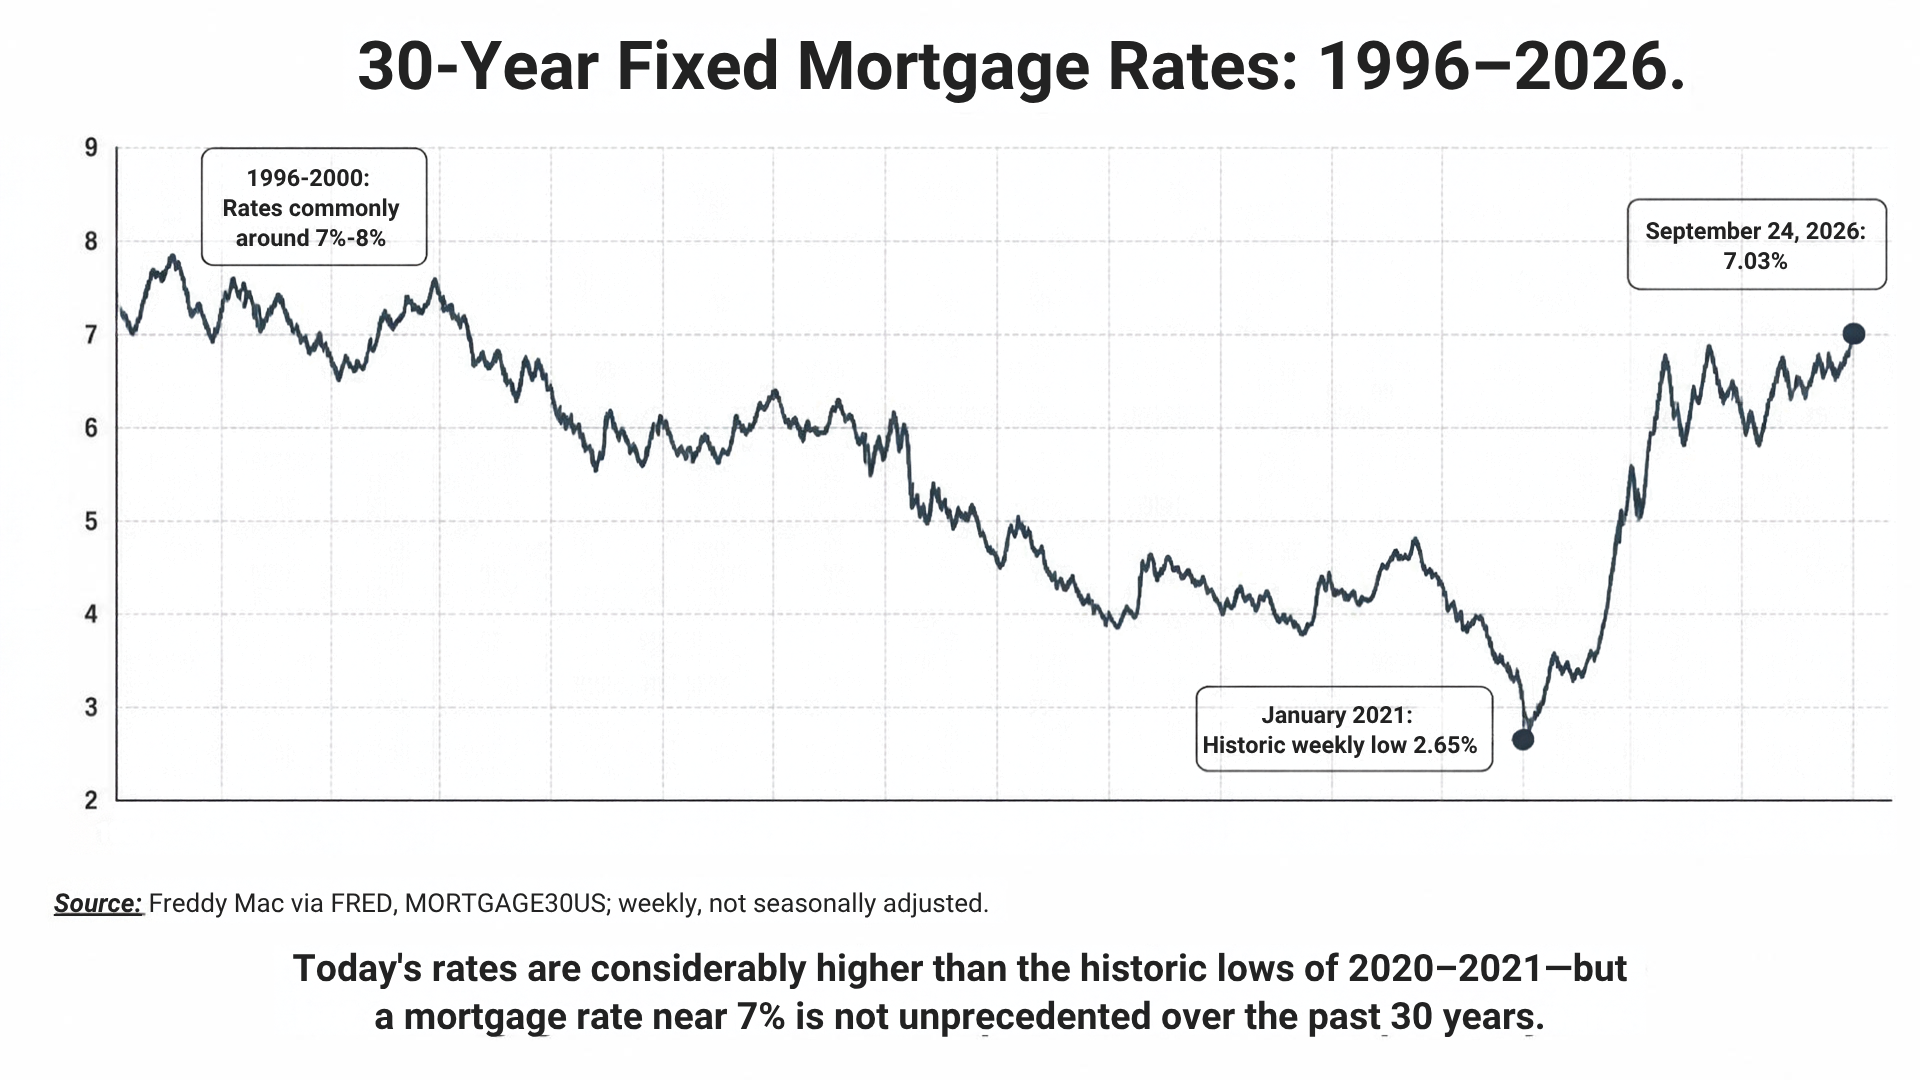
Mortgage rates near 7% can make buying a home feel very different from the low-rate environment of recent years. But higher rates do not necessarily mean buyers should step away from the market.
With borrowing costs higher and more homes available in many markets, buyers can focus on strategies that make a purchase more manageable.
Focus on the Monthly Payment
Instead of starting with the maximum price a lender approves, consider the monthly payment that comfortably fits your budget. Remember to account for property taxes, insurance, HOA fees, maintenance, and other homeownership costs.
Compare Mortgage Options
Shopping with multiple lenders can help you compare interest rates, fees, points, and loan terms. If you're considering discount points to lower your rate, calculate how long it would take for the monthly savings to offset the upfront cost.
Look for Negotiating Opportunities
More inventory can give buyers additional options and, in some markets, more room to negotiate. Depending on the property and seller, buyers may be able to discuss a lower price, closing-cost contributions, repair credits, or other concessions.
Protect Your Savings
A larger down payment can reduce your loan balance, but it also means using more of your available cash. Keeping an emergency reserve for moving expenses, repairs, and unexpected costs can be an important part of preparing for homeownership.
Buy Based on Today's Numbers
It can be tempting to assume you'll refinance when rates fall. However, future rates cannot be guaranteed. Make sure the home and mortgage payment work for your budget today. A future refinancing opportunity can be considered a bonus.
Take a Strategic Approach
Today's market requires buyers to look beyond the mortgage rate alone. Price, financing, property condition, taxes, insurance, and negotiating opportunities all play a role.
If you're considering buying this fall, getting prepared early can help you understand your options and make decisions with greater confidence.